Dealmaker Q&A

Content available in English and Portuguese (scroll down)

TTR DealMaker Q&A with Lefosse Advogados Partner Luiz Octavio Lopes
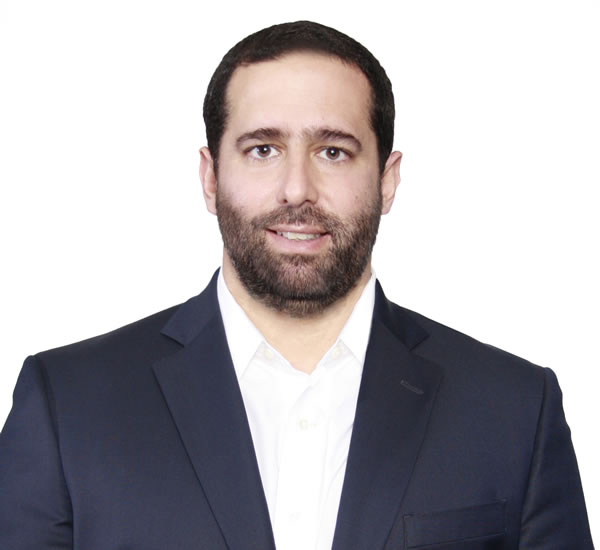
Luiz Octavio Lopes – Lefosse Advogados

Luiz Octavio joined Lefosse in 2015 as a partner and has extensive experience in Corporate Finance transactions, having acted as leading advisor in a large number of corporate and capital market transactions in Brazil and abroad. Luiz Octavio is recognized by LACCA Approved as a lawyer recommended in Capital Markets by members of the renowned Latin American Corporate Counsel Association, linked to the Latin Lawyer group. Prior to joining Lefosse, Luiz Octavio was a Managing Director at Credit Suisse’s investment banking group for 5 years, where he acted as Head of the M&A for Brazil and coverage banker. Previously, he was as partner at Mattos Filho, Veiga Filho, Marrey Jr. & Quiroga. He obtained his Law degree from the Universidade do Estado do Rio de Janeiro and his LL.M. from New York University.


TTR: How would you describe the current situation of the players in the transactional market in Brazil in this “new reality”?

L. O. L.: The transactional market in Brazil is going through a very positive phase. In spite of the pandemic, our capital market is extremely active. At the moment Lefosse alone is involved in around 40 IPO transactions. If this trend continues we shall see a record volume of M&A transactions in 2021. 

A number of law firms, including our own, were well placed to take advantage of this and have adjusted their staffing accordingly. At the same time, we have not experienced any loss of quality or decrease in productivity because of the need for people to stay away from the office or from the implementation of remote work practices. Probably the biggest challenge has been to disseminate and absorb corporate culture at a time when personal contact and casual encounters have not been possible.

TTR: Lefosse Advogados is ranked by TTR as one of the top legal advisors  for Brazilian healthcare sector M&A transactions. How do you see the growth in the sector during the first half of 2021 and what are the medium and long-term prospects?

L. O. L.: The trend for consolidation has been a feature of the healthcare sector since 2015, when the law in Brazil was changed to allow foreigners to invest in healthcare. Since then a number of companies have floated their shares on the local stock exchange or have attracted funds from private equity investors. 

What we have been seeing in 2021 is simply an acceleration of this trend, fuelled by factors such as easier credit and the fact that certain companies – under the influence of the pandemic – are now open to strategic possibilities that they might not have contemplated if things were different.

The truth is that, even with all the consolidation that has gone on in recent years and the initiatives for making private healthcare more widely accessible, a large portion of the population still depends on the National Health Service (the SUS), which represents a series of challenges, especially concerning the differences between services provided by the public and private health sectors in Brazil. In other words, the area still has huge potential for growth that is not tied to an increase in the population. Instead, this growth could be achieved by attracting clients looking for better service from private initiative.

Added to this, the sector has other major growth fronts, such as the opportunities arising from the development of health techs. Sectors with substantial potential for growth are, traditionally, attractive from a transactional viewpoint. So we are very optimistic about the healthcare sector, and we expect the volume of transactions in this area to continue to grow.

TTR: What key challenges will  Lefosse Advogados face for M&A transactions in Brazil during 2021?

L. O. L.: The pandemic created a lot of challenges. We have had to adjust to a new reality and working from home has imposed changes to both behaviour and procedures. It is safe to say that the requirements for people to work from home and meetings  held on Zoom have significantly affected the lives of all our staff.  

TTR: Purchases by foreign buyers of tech and internet companies in Brazil were up by 134% in the first half of 2021. What will be the key vectors for consolidation in these segments over the course of the year?

L. O. L.: The increased volume of M&A transactions in the tech sector is a symptom of the global trend for convergence between the industries which has been stimulated by technological disruptions. We believe that the consolidation vectors of the technology sector will continue to be linked to these principles. However, we also think that they will be intensified as a result of the pandemic which has created a need for companies to speed up digitalization and the transformation of their businesses.


Portuguese version


Luiz Octavio Lopes – Lefosse Advogados

Luiz Octavio é sócio dá área de Corporate Finance e possui ampla experiência transacional, tendo atuado como leading counsel em um grande número de operações societárias e de mercado de capitais, no Brasil e no exterior. Ele é reconhecido pelo LACCA Approved como advogado recomendado na área de Capital Markets pelos membros da renomada Latin American Corporate Counsel Association, vinculada ao grupo Latin Lawyer. Antes de se juntar ao Lefosse, Luiz Octavio atuou como Managing Director no grupo de banco de investimento do Banco Credit Suisse, onde foi Head da área de M&A no Brasil. Previamente, foi sócio do Mattos Filho, Veiga Filho, Marrey Jr. & Quiroga. Luiz Octavio é formado em direito pela Universidade Estadual do Rio de Janeiro e recebeu o título de mestre em direito (LL.M) pela New York University School of Law – NYU.


TTR: Como você descreveria a situação atual dos players no mercado transacional no Brasil nesta “Nova Realidade”?

L. O. L.: O mercado transacional passa por um momento bastante positivo no Brasil. Mesmo com a pandemia, temos um mercado de capitais bastante aquecido – atualmente, apenas no Lefosse, estamos trabalhando em aproximadamente 40 operações de IPO. Seguindo a mesma tendência, estamos tendo em 2021 volumes recorde em transações de M&A. 

Diversos escritórios, assim como o nosso, estavam posicionados e ajustaram os seus quadros para aproveitar o bom momento. Da mesma forma, não vivenciamos qualquer perda de qualidade ou queda de produtividade decorrente da necessidade do afastamento físico das equipes e da implementação de estruturas de trabalho remoto. Provavelmente, o maior desafio enfrentado por todos esteja associado à propagação e absorção da cultura de cada instituição em um momento que contatos pessoais e encontros casuais não são possíveis.

TTR: Lefosse Advogados é um dos principais assessores de M&A do setor de saúde do Brasil de acordo com o ranking jurídico do TTR. Como você avalia o crescimento do setor no primeiro semestre de 2021 e quais as perspectivas de médio e longo prazo?

L. O. L.: O movimento de consolidação no setor de saúde é um fenômeno que se observa desde 2015, quando a legislação brasileira passou a admitir investimentos de capital estrangeiro na assistência à saúde no Brasil. Desde então, diversas empresas do setor abriram o capital na bolsa de valores ou receberam investimentos de fundos de private equity. 

O que vimos em 2021 foi apenas um desdobramento dessa tendência, potencializada por fatores como o aumento da oferta de crédito e o fato de determinadas empresas, em razão dos impactos da pandemia, terem se aberto a possibilidades estratégicas que poderiam não contemplar em um cenário diferente.

A verdade é que, mesmo com todo o movimento de consolidação experimentado nos últimos anos e as iniciativas de democratização do acesso à saúde por meio da iniciativa privada, uma grande parte da população ainda depende do SUS e os desafios são muitos, principalmente em relação à diferença nos serviços oferecidos pelos setores privado e público de saúde no Brasil. Ou seja, ainda existe um grande espaço para expansão do setor, independentemente do crescimento da população, mediante a captura de vidas que buscam na iniciativa privada uma melhor assistência.

Ademais, o setor apresenta frentes adicionais de crescimento importantes, como a decorrente do desenvolvimento das health techs. Setores com grande potencial de crescimento são, tradicionalmente, atrativos da perspectiva transacional. Assim, olhamos com bastante otimismo para o setor de saúde, e a nossa expectativa é que volume de operações neste setor continue crescente.

TTR: Quais serão os principais desafios da operação de M&A no Brasil durante 2021 para o Lefosse Advogados?

L. O. L.: Mais do que desafios, a pandemia trouxe a necessidade de nos ajustarmos a uma nova realidade; o trabalho remoto impôs mudanças de comportamentos e rotinas. Certamente, o home office obrigatório e a realização de reuniões via teleconferência estabeleceram uma dinâmica diferente na vida de todos os membros de nossa equipe.  

TTR: As aquisições por compradores estrangeiros de empresas de tecnologia e Internet no Brasil aumentaram 134% no primeiro semestre de 2021. Quais serão os principais vetores de consolidação desses segmentos ao longo do ano?

L. O. L.: O crescimento no volume de operações de M&A no setor de tecnologia está intimamente ligado às tendências globais de convergência entre as indústrias, estimulada por disrupções tecnológicas. Acreditamos que os vetores de consolidação do setor de tecnologia continuarão atrelados a esses mesmos princípios, mas serão intensificados pela pandemia, que gerou a necessidade de empresas acelerarem a digitalização e a transformação dos seus negócios.
Dealmaker Q&A

Content available in English and Portuguese (scroll down)

TTR DealMaker Q&A with Bronstein Zilberberg Advogados Founding Partner Sergio Bronstein

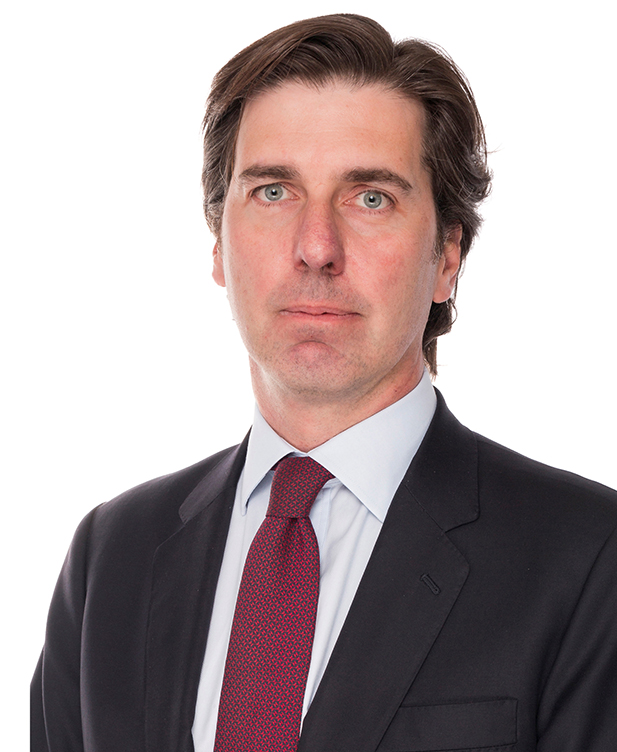
Sergio Bronstein – Bronstein Zilberberg Advogados

Sergio Bronstein is a founding partner of the firm and co-head of its M&A and Venture Capital practices. Sergio is a senior and well-seasoned M&A lawyer, recognized as one of the most active and experienced Brazilian dealmakers in the past five Years.
His clients include companies from a full array of sectors, including technology companies, VC, PE funds and CVCs


TTR: What’s your outlook for the M&A market in 2021?

S.B.: The M&A market in 2021 has been booming and the number and volume of transactions skyrocketed in the past year amid the pandemic and the need for digital transformation for all companies around the globe. We believe the pace will continue throughout the 3rd and 4th quarters of this year and we will not be surprised to see an increase in the number of M&A deals led by growth companies.

TTR: Foreign acquisitions of technology and Internet companies in Brazil have increased 134% in 2021. What will be the main drivers of consolidation in these segments over the course of the year?

S.B.: The main drivers of consolidation will remain in the fintech, online retail and proptech segments. Agtech and healtech are also very attractive due to the large room for improvement and digital transformation in these fields. Adding to this perfect storm scenario are the excess cash, the Real depreciation, newly funded investment vehicles and the continental size of the Brazilian market.

TTR: What does the dissemination of fintech platforms imply for access to the capital market in Brazil in the short and medium term?

S.B.: The dissemination of fintech platforms certainly contributes to a more client driven approach in the financial industry, thus enabling better solutions, credit alternatives and lower fees. The advantages are not simply related to the access to capital markets but to a broader base of financial products and a larger array of products made available to the general public. 

TTR: What would be another three sectors that could offer the greatest opportunities in Brazil for international investors in 2021 and why?

S.B.: Marketplaces, software companies and logistics are key sectors which will remain attracting attention of foreign investors. All three combine digital transformation with new habits fast-tracked during Covid-19 and also represent an immense market opportunity for better services and value creation.

TTR: What will be the main challenges for Bronstein Zilberberg Advogados in its M&A advisory work in Brazil in 2021?

S.B.: The firm was established 3 months ago and is a true digital native firm with all 50+ members still working remotely due to the pandemic. Having assisted clients in over 30 deals during this period, we realized that working remotely did not impact our performance. Nevertheless, the entire team is looking forward to meeting face to face and being able to work together and interact at the same premises. Perhaps for the first time in history, lawyers are eager to have more face to face interactions rather than spending their time at home.


Portuguese version


Sergio Bronstein – Bronstein Zilberberg Advogados

Sergio Bronstein é sócio fundador do escritório e co-lidera as práticas de M&A e Venture Capital. Sergio é um advogado experiente em operações de M&A, sendo reconhecido como um dos mais ativos e determinados dealmakers nos últimos cinco anos.
Sua gama de clientes combina os mais variados setores, incluindo empresas de tecnologia, fundos de Venture Capital, Private Equity e ainda alguns fundos de Corporate Venture Capital.


TTR: Qual é a sua perspectiva para o mercado de fusões e aquisições em 2021?

S.B.: O mercado de M&A em 2021 está muito prospero e o número e volume de operações explodiu no último ano em meio a pandemia e a necessidade de transformação digital. de todas as empresas ao redor do mundo. Acreditamos que o 3o e 4o trimestres deste ano manterão o ritmo visto e não nos surpreenderemos se houver um número ainda maior de transações de M&A liderados por empresas de alto crescimento.

TTR: As aquisições por compradores estrangeiros de empresas de tecnologia e Internet no Brasil aumentaram 134% em 2021. Quais serão os principais vetores de consolidação desses segmentos ao longo do ano?

S.B.: Os maiores vetores de consolidação continuarão sendo no segmento de fintechs, varejo online e proptechs. As agtechs e healthtechs continuarão sendo muito atrativas devido ao grande espaço para melhorias nessas áreas e a transformação digital verificada nestes segmentos. Soma-se a esse cenário de tempestade perfeita para investimentos o excesso de dinheiro disponível no mundo, a desvalorização do Real, novos fundos capitalizados e o tamanho continental de um país como o Brasil.

TTR: O que significa a disseminação das plataformas fintech para o acesso ao mercado de ações no Brasil no curto e médio prazo?

S.B.: A disseminação das plataformas fintech certamente contribui para uma indústria financeira mais focada ao cliente, permitindo desta forma melhores soluções, mais alternativas de crédito e taxas menores. As vantagens não são simplesmente relacionadas a acesso ao mercado de capitais, mas fundamentalmente a uma base maior de produtos financeiros e de uma gama maior de produtos destinadas ao público em geral.

TTR: Quais seriam os outros três setores que poderiam oferecer as maiores oportunidades no Brasil para investidores internacionais em 2021 e por quê?

S.B.: Marketplaces, desenvolvedores de software e empresas de logística serão setores chave que permanecerão atraindo a atenção de investidores estrangeiros. Todos os três combinam o tema da transformação digital aliada a novos hábitos digitais acelerados durante a pandemia, representando oportunidades enormes de mercado para melhorias nestes serviços e áreas e criação de valor.

TTR: Quais serão os principais desafios da operação de M&A no Brasil durante 2021 para o Bronstein Zilberberg Advogados?

S.B.: O escritório nasceu virtualmente há 3 meses com uma marca nativa verdadeiramente digital e com todos os seus mais de 50 colaboradores trabalhando remotamente. Este tem sido um grande desafio desde o 1o dia de nossa história e todo o time aguarda ansiosamente para se encontrar presencialmente e continuar nossa jornada num mesmo lugar físico. Creio que será a primeira vez na história moderna da advocacia que advogados estão ansiosos para passar mais tempo no escritório e não em suas casas.

Dealmaker Q&A

Content available in English and Spanish (scroll down)

TTR DealMaker Q&A with UNE Asesores Financieros Founding Partner and CEO Ian Fry Cisneros

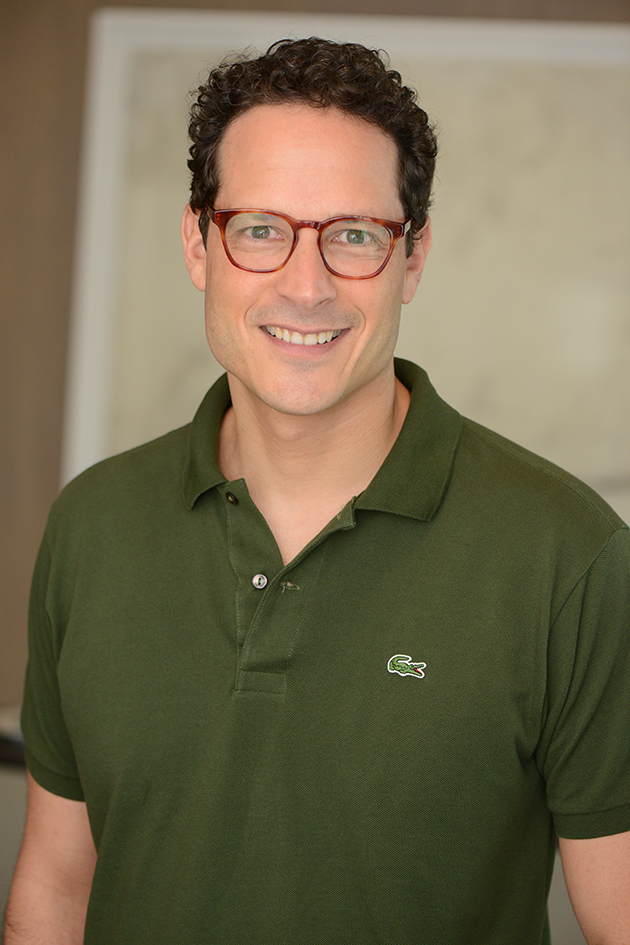
Ian Fry Cisneros – UNE Asesores Financieros

Founder and current Executive Director of UNE Asesores. Bachelor of Business Administration at Universidad del Pacífico. He holds an MBA from the London Business School. He has also obtained a trader certification from the Financial Services Authority in Great Britain. He previously held the position of Commercial Strategy Manager of investment products at Banco de Crédito. He has also held the position of associate at the structured products desk at Bank of America in London, and worked as senior analyst and head of investment products at Citibank.

.


TTR: What will be the most relevant drivers for the consolidation of the M&A market in the medium and long term for the country and Latin America?

I.F.: We see an important increase of cross-border transactions between counterparts in Latin America. This implies a high level of interactions among advisors, as a result of remote work and increase in the adoption of digital tools. At UNE, we are currently serving companies in Perú and have recently extended them to Colombia and Brazil. For example, in Brazil we are attending a sell- side M&A in the airport F&B segment.

At this point in time, it´s necessary carrying out a greater level of detail when constructing a valuation model. This would make them much more flexible, accurate and easier to update regarding the changing perspectives and expectations in the region.

Furthermore, we see a higher level of creativity in the structures proposed by advisors. Earn outs are a helpful tool to possible to close gaps between the expectations of buyers and sellers.

TTR: Which market segments present the greatest opportunities for international investors in 2021, and why?

I.F.: From our perspective the greatest opportunities for international investors are the sectors that have managed a positive outcome during 2020 and those who have experienced post-pandemic growth. Sectors such as IT, industrial, logistics and health are experiencing robust M&A activity. In particular, the corporate health segment is requiring greater demands and protocols in order to minimize health and safety risks at work.

TTR: What will be the main impacts on the M&A market in Peru of the new antitrust legislation?

I.F.: The new antirust legislation in Perú impacts directly on the M&A market by extending the close transactions processes, as there would be a waiting window for the regulator’s decision. However, we believe that this law would put foreign companies, with little or no presence in Peru, in a better position to acquire companies compared to the local players that already have a significant presence in the country.

TTR: How will the current political environment in Peru affect the dynamics of the M&A market?

The political electoral situation generated a greater uncertainty in the local market, particularly affecting large transactions over US$ 300 million and those sectors, such as mining and infrastructure, that would have a negative outcome depending on the electoral result. However, we continue to see dynamism in the segment of medium-sized companies thanks to the liquidity and interest of investment funds. Thus, we could see a period where some entrepreneurs decide to pursue a liquidity event by selling their companies in order to migrate to more traditional investment alternatives.

TTR: What will be the greatest challenges for UNE in its M&A advisory work in Perú in 2021?

I.F.: UNE´s greatest challenges is to close the transactions that are in the pipeline by normalizing the atypical results of those companies affected by the pandemic during 2020. These normalized

results would be the basis for projections and a better and more accurate valuation of these companies.

In addition, we seek to increase our presence at the regional level and strengthen the alliances already established with other boutiques in Latin America. We are currently serving clients in Perú, Colombia and Brazil, so our next milestone is to begin serving clients in Ecuador and Bolivia.

TTR: Following the previous answer, what do you think will allow UNE to successfully carry out this greater regional presence?

I.F.: Unlike other investment banking boutiques that cover various financial services, UNE’s pillar, and what has allowed it to differentiate itself, is its focus on advising on the purchase or sale of medium-sized companies valued between US$ 10 million and US$ 100 million. Our services rely on advising and representing the owners throughout the sale process of their companies in order to achieve better terms for them. Extensive experience and professionalism in selling medium sized companies makes us have a very important and differentiating attribute compared to other players in the market. Our typical client has extensive knowledge of the industry in which he develops from his years leading his business, but when evaluating to incorporate a partner or fully sell his company, he requires an experienced financial advisor.

Likewise, when we are on the buyer’s side, the experience of serving family businesses helps us prospect and find good targets as well as conducting negotiations in the best way.

TTR: Are they typically family businesses?

I.F.: Yes, they are companies that have been developed in a personal way. Ventures that have been successful in recent years and that today reach a significant size. Our objective is to advise those Latin American entrepreneurs, owners of successful medium-sized companies, who want to sell their company to a larger player in the sector or perhaps incorporate a strategic partner.

TTR: Usually who are the buyers of the companies that UNE advises?

I.F.: The buyers vary depending on each company and industry, they are economic groups or regional private equity funds. There is a strong appetite in the Latin American market and we perceive interest from capital to invest in the region. Thus, we survey the market and get in touch with the natural buyers for each company that we advise.

Notwithstanding this, we serve more sophisticated corporate clients when they are interested in acquiring targets in this segment related to family or medium-sized businesses.

TTR: So, do you also advise on the buy-side of companies?

I.F.: Yes, we advise foreign companies that want to enter Peru through the purchase of a local ventures, as well as Peruvian groups interested in acquiring another company or selling a division or an asset in their portfolio. Usually in these cases the target is a family or medium-sized company, where our main expertise lies.

TTR: How has transactional activity been at UNE during this year?

I.F.: So far this year we have closed four transactions, the most importants involve two of Peru’s leading economic groups, Alicorp and Aceros Arequipa. In the first one, we advised Vegetalia (a family company with more than 50 years of experience in the oil industry) in the sale to Alicorp. In this case, the owners had never gone through a sale process and after a detailed market analysis and a hard negotiation, it was successfully sold to Alicorp. In the second case, we advised several second and third generation family groups in the sale of COMFER (a company with more than 30 years of experience, dedicated to the commercialization of steel products) to Aceros Arequipa.

UNE’s advisory adds value to these families providing expertise, technical knowledge and a network of contacts in the region.   


Spanish version


Ian Fry Cisneros – UNE Asesores Financieros

Fundador y actual Director Ejecutivo de UNE Asesores. Bachiller en Administración de Empresas en la Universidad del Pacífico. Cuenta con un MBA del London Business School. Asimismo, ha obtenido la certificación de trader del Financial Services Authority en Gran Bretaña. Fue gerente de Estrategia Comercial de productos de inversión en el Banco de Crédito. Asimismo, ocupó el cargo de asociado en la mesa de productos estructurados en Bank of America en Londres. Además, fue analista senior y jefe de productos de inversión del Citibank.


TTR: ¿Cuál es la tendencia actual en el servicio de asesoría financiera en LatAm? 

I.F.: Vemos un mayor nivel de transacciones cross border, contando con contrapartes en otros países e interacción de asesores basados en diferentes países, producto del incremento del trabajo remoto y la adopción de mayores herramientas digitales. En UNE ya estamos atendiendo a empresas en Colombia y Brasil, por ejemplo, en Brasil estamos atendiendo a un cliente en el segmento food & beverages en aeropuertos.

Vemos también necesario el realizar un mayor nivel de detalle al armar los modelos de valorización, muchos más flexibles que permitan actualizar fácilmente las perspectivas y expectativas cambiantes en la región.

Por otro lado, vemos un mayor nivel de creatividad en las estructuras por parte de los asesores. Por ejemplo, los earn outs permiten cerrar brechas entre las expectativas de compradores y vendedores. Ahí, el rol que de los asesores financieros es clave

TTR: ¿Cómo podrían resumir el primer semestre en la actividad de M&A en el Perú?

I.F.: Durante el primer trimestre en Perú, entró en vigencia la ley de control de fusiones y adquisiciones, lo cual aceleró la actividad de los procesos transaccionales que estaban próximos a cerrar.

El segundo trimestre se caracterizó principalmente por la incertidumbre electoral de las elecciones presidenciales. Esto generó una mayor incertidumbre y una alta aversión al riesgo en el mercado local, afectando en particular las transacciones grandes, superiores a US$ 300 MM, y aquellas que se verían muy afectadas en función al resultado electoral, como lo son sectores ligados a minería o infraestructura

No obstante, en el rubro de empresas medianas, continúa el dinamismo de las transacciones de M&A. Vemos que persiste mucha liquidez a nivel global, niveles de tasas bajas e interés en invertir en mercados emergentes. En ese sentido, en UNE seguimos atiendo muchos empresarios que están activamente buscando la venta de sus empresas.

TTR: ¿Cuáles serían los sectores que podrían ofrecer las mayores oportunidades en Perú a los inversores internacionales en 2021 y por qué?

I.F.: Desde nuestra perspectiva, indudablemente los sectores que se han visto beneficiados y han experimentado un crecimiento post-pandemico. Sectores como el de tecnología y desarrollo, industrial, logística y aquellos que han sido beneficiados por los efectos de pandemia, como lo es el sector salud. En particular, el segmento de salud corporativo, está requiriendo mayores exigencias y protocolos con el objetivo de minimizar riesgos de salud y seguridad en el trabajo. Así, países como México, Brasil, Chile y Colombia podrían ser los mayores interesados por la actividad que han tenido en las transacciones de M&A durante el primer trimestre del 2021.

TTR: ¿Cuáles serán los principales impactos que se podrán generar en el mercado M&A de Perú con la entrada en vigor de la nueva ley sobre control previo en el país?

I.F.: Un mayor tiempo en realizar el cierre de la transacción pues habría una ventana de espera de la decisión del regulador sobre la transacción. Sin embargo, creemos que esta ley pondría a compañías del exterior, con poca o nula presencia en Perú, en mejor situación para adquirir empresas, a comparación de compañías locales que ya cuentan con una presencia significativa en el Perú.

TTR: ¿En qué medida afectará el actual entorno político de Perú a la dinámica del mercado de Fusiones y Adquisiciones?

I.F.: La coyuntura electoral generó una mayor incertidumbre en el mercado local, afectando en particular las transacciones grandes superiores a US$ 300 MM o ligadas al resultado electoral como aquellas en los sectores de minería o infraestructura. Sin embargo, continuamos viendo dinamismo en el segmento de empresas medianas gracias a la liquidez e interés de fondos de inversión, así, podríamos ver un periodo donde algunos empresarios decidan realizar un evento de liquidez vendiendo sus compañías para así migrar a alternativas de inversión mas tradicionales y líquidas, lo cual generaría un mayor dinamismo en el mercado.

TTR: ¿Cuáles serán los principales desafíos en términos de transacciones de M&A en Perú durante 2021 para UNE Asesores?

I.F.: Concretar las transacciones que están en el pipeline, normalizando los resultados atípicos que han tenido muchas compañías que han sido afectadas por la pandemia, para que estos sean las bases de las proyecciones.

Además, incrementar nuestra presencia a nivel regional y afianzar las alianzas ya establecidas con otras boutiques de Latinoamérica. Actualmente estamos atendiendo a clientes de Colombia y Brasil, así, nuestro siguiente hito es empezar a atender clientes en Ecuador y Bolivia.

TTR: En esa línea, ¿qué creen que les permitirá realizar acabo de forma exitosa esta mayor presencia regional?

I.F.: A diferencia de otras boutiques de banca de inversión que abarcan varios servicios financieros, el pilar de UNE, y lo que le ha permitido diferenciarse, es su enfoque en la asesoría de compra o venta de empresas medianas valoradas entre US$ 10 millones y US$ 100 millones. Lo que hacemos es asesorar y representar a los dueños durante todo el proceso de venta de sus compañías a fin de lograr mejores términos para ellos. Nuestra amplia experiencia y expertise en vender empresas medianas, hace que poseamos un atributo muy importante y diferenciador respecto a otros jugadores del mercado. Nuestro cliente típico posee amplio conocimiento de en la industria en la que se desarrolla por sus años liderando su negocio, pero que al momento de evaluar incorporar a un socio o de vender totalmente su empresa, requiere de un asesor financiero con experiencia.

Asímismo, cuando estamos del lado del comprador, la experiencia de atender a empresas familiares, nos ayudar a prospectar y encontrar buenos targets como también conducir las negociaciones de la mejor forma.

TTR: ¿Típicamente son empresas familiares?

I.F.: Sí, son empresas que se han desarrollado de manera personal. Emprendimientos que en los últimos años han sido exitosos y que hoy alcanzan un tamaño relevante. Nuestro objetivo es asesorar a esos empresarios latinoamericanos, dueños de empresas medianas exitosas, que quiere vender su compañía a un jugador más grande del rubro o quizá incorporar algún socio estratégico.

TTR: ¿Usualmente quienes son los compradores de las empresas que asesora UNE?

I.F.: Los compradores varían dependiendo de cada empresa e industria, son los grupos económicos o fondos de private equity regionales. Existe mucha liquidez en el mercado latinoamericano y percibimos interés del capital para invertir en la región. Así, sondeamos el mercado y nos ponemos en contacto con los compradores naturales de cada empresa que asesoramos.

Sin perjuicio de ello, atendemos a clientes corporativos más sofisticados cuando están interesados en adquirir targets de este segmento relacionado a la empresa familiar o de tamaño medio.

TTR: ¿Entonces, asesoran también en la compra de empresas?

I.F.: Sí, asesoramos a empresas extranjeras que quieren entrar al Perú a través de la compra de una empresa local, así como a grupos peruanos interesados en adquirir una compañía o vender alguna división o empresa de su portafolio; usualmente en estos casos el target es una empresa familiar o de tamaño medio, donde está nuestro expertise principal.

TTR: ¿Cómo ha estado la actividad transaccional en UNE durante el año?

En lo que va de este año hemos cerrado cuatro transacciones, siendo las más importantes las que involucran a dos principales grupos económicos del Perú como lo son Alicorp y Aceros Arequipa. En la primera, asesoramos a Vegetalia (empresa familiar con +50 años de experiencia en la industria oleoginosa) en la venta a Alicorp. En este caso, los dueños nunca habían pasado por un proceso de venta y luego de analizar el mercado y negociar con Alicorp se vendió exitosamente. En cuanto a la segunda, asesoramos a varios grupos familiares de segunda y tercera generación en la venta de COMFER (empresa con +30 años de experiencia, dedicada a la comercialización de productos derivados del acero) a Aceros Arequipa.

La asesoría de UNE a estas familias, les agrega valor pues brindamos expertise, conocimiento técnico y una red de contactos en la región.   

Dealmaker Q&A

Content available in English and Spanish (scroll down)

TTR DealMaker Q&A with Udekta Capital and Udekta Corporate Founding Partner and Director Juan Sainz de los Terreros

Juan Sainz de los Terreros – Udekta Capital and Udekta Corporate

Founding partner and director of Udekta Capital, an independent investment vehicle focused on European microcaps. Founding partner and director of Udekta Corporate, a financial boutique specialised in alternative stock markets and dedicated to advising companies.


TTR: Udekta Capital was set up in December 2016 as an independent and pioneering investment vehicle to invest in BME Growth companies (former MAB) and pre-market companies (pre-MAB). How did the idea come about?

J.S.T.: After several years working in the financial sector and after several private investments in companies listed on the former MAB, now called BME Growth, a small group of people decided to create a private investment vehicle focused on small listed companies in Spain. We all understood that the potential of these companies was spectacular, after a good job of analysis and monitoring and with a long-term vision. There was hardly anything like it in the whole sector. Microcaps were not an attractive asset for the industry for various reasons such as liquidity and volatility, among others. Therefore, not only did we think that this vehicle was going to give us great results after a reasonable period of time, but we also understood that it was very interesting to demonstrate to the industry that this type of asset has a lot of potential, if done from a professional perspective, and that more vehicles of this type should be created in Spain.

TTR: Udekta Capital was set up with an initial capital of 200,000 euros with the idea of investing in four or five companies. What is the current status of the vehicle?

J.S.T.: We wanted to start with a small amount as we were aware of the investment limits in this type of company. Today we are around one million euros and we have gone from being 8 shareholders to 17 in these four and a half years of the vehicle’s life. We are invested in 14 companies. We have made some divestments and our main positions are: GUILLEMOT, GIGAS, ALTIA and IZERTIS.

TTR: Initially, Udekta Capital focused on companies listed in the EE segment, not in Socimis, and had no predilection for any sector. Have you changed the criteria?

J.S.T.: We remain focused on Growth Companies in any sector except SOCIMIS but we have made the leap to European microcaps. We are invested in two listed on Euronext (Paris) and one listed on AIM (London).

“There are several sectors that are going to have a very positive trend over the next few years and that will be interesting to invest in. Among them we could highlight the ICT sector, telemedicine and eSports.”

TTR: The Mercado Alternativo Bursátil (MAB) changed its name in 2020 and is now called BME Growth, after obtaining SME Growth Market status, granted by the Spanish Securities Market Commission (CNMV) and recognised by MiFID. What significant changes have there been since then?

J.S.T.: From our point of view, there is not much new after the change of name or the upgrading of SME Growth Market. It is still an alternative stock market aimed at small and medium-sized companies, although it is true that it has the European seal of quality as SME Growth Market and that it’s more open to the international market.

TTR: What kind of companies are currently listed on BME Growth, are they trading at interesting prices and are they achieving the expected returns?

J.S.T.: We always find interesting opportunities in BME Growth. There are more and more companies with attractive expansion projects. As in all markets, we will find good and bad companies. But with a good selection, the returns are extraordinary. The shareholders of Udekta Capital are very satisfied with the results we have obtained in the four and a half years of the vehicle’s life. In this period, we have more than doubled the return on our investments.

TTR: What would it take for BME Growth in Spain to reach the same market level as in other countries?

J.S.T.: I believe that more companies need to join, more information about the asset class needs to be made available, more training needs to be offered to entrepreneurs to support them in the process of joining the market, and the risks and opportunities of investing in microcaps need to be explained to investors.

TTR: What are the keys for an SME to decide to go public in Spain?

J.S.T.: In general terms, I would say that an SME must be clear that listing on the stock market is possible and that it brings many benefits in terms of financing, visibility, notoriety, liquidity of its shares and having a valuation of the company accepted by the market. From there, entrepreneurs and managers of companies that want to be listed on a market such as BME Growth must be aware that being a listed company requires professionalism, transparency, budgeting for higher structural costs and offering special dedication in terms of investor relations.

TTR: The technology sector and renewable energies are the sectors that seem to have seen the greatest evolution in the M&A and private equity sector in recent months. Which sectors do you see as having the best medium-term prospects?

J.S.T.: From our point of view, there are several sectors that are going to have a very positive trend over the next few years and that will be interesting to invest in. Among them we could highlight the ICT sector (Information and Communication Technologies), all companies related to telemedicine and the eSports sector.

“Udekta Sports will have a life of its own in the medium term, although it is now being developed within Udekta Capital and we have invested in the Olympique de Lyon Group, which has a number of assets in addition to the men’s and women’s football teams.”

TTR: In parallel to the creation of Udekta Capital, UDEKTA Corporate was created as a financial boutique dedicated to advising companies, mainly in the steps prior to their listing on the MAB. How has your activity evolved?

J.S.T.: We are seeing an increase in the interest of SMEs in going public and this situation is very important to us. In 2017, we created Udekta Corporate with the aim of advising companies in different areas (legal, financial, labour…) and with the differentiation of being a boutique specialising in alternative stock markets. There is no doubt that the growth in the number of companies listed on the BME Growth in recent years and the success stories that this market has produced, such as MASMOVIL or GRENERGY, are helping to attract more companies. 

UDEKTA Corporate’s activity is growing year after year. We are currently working with several listed companies in this market in the field of Investor Relations. In addition, we are advising other unlisted companies. The timeframe we usually set ourselves for coordinating a listing on a market such as BME Growth is between 18 and 24 months. In this sense, we expect some of these companies to be listed on this market in 2022.

TTR: At the end of 2019 you announced the creation of Udekta Sports, an investment vehicle focused on European football teams listed on the stock markets. How is this project going?

J.S.T.: As we know, March 2020 was a life-changing month for us with the appearance of Covid-19. We had high expectations for the project, but we had to put it on hold for a while. Logically, creating an exclusive vehicle to invest in football teams and in any sport when stadiums were empty, people were confined and uncertainty was at its peak, made us put the project on “pause”. 

However, what we have done is to invest in an internationally listed football club through Udekta Capital. Specifically, we have invested in the Olympique Lyon Group which owns, among other assets, the men’s and women’s football teams of Olympique Lyon itself. The investment thesis is almost single-handedly supported by the football stadium as a real estate asset. For us, this asset would be worth considerably more than the capitalisation and debt of the club. The stadium, in addition to being the field where the football team plays, supports other corporate events, concerts and many activities other than those related to the football club. In fact, even if the football team were to disappear, the stadium would already have a higher valuation than its stock market valuation. In short, Udekta Sports is currently being developed within Udekta Capital, but we want it to take on a life of its own as soon as possible.


Spanish version


Juan Sainz de los Terreros – Udekta Capital and Udekta Corporate

Socio fundador y consejero de Udekta Capital, vehículo de inversión independiente con el foco puesto en las microcaps europeas. Además, es socio fundador y consejero de Udekta Corporate, boutique financiera especializada en mercados alternativos bursátiles y dedicada al asesoramiento a empresas.


TTR: Udekta Capital se constituyó en diciembre de 2016 como vehículo de inversión independiente y pionero para invertir en empresas del BME Growth (antiguo MAB) y en compañías preMercado (preMAB). ¿Cómo surge la idea? 

J.S.T.: Tras varios años trabajando en el sector financiero y tras varias inversiones particulares en compañías cotizadas en el antiguo MAB, actualmente denominado BME Growth, un pequeño grupo de personas decidimos crear un vehículo privado cuyo foco de inversión estuviera en las pequeñas compañías cotizadas en España. Todos entendíamos que el potencial de estas empresas era espectacular, tras un buen trabajo de análisis y seguimiento y con una visión de largo plazo. Apenas existía nada parecido en todo el sector. Las microcaps no eran un activo atractivo para la industria por varios motivos como la liquidez y la volatilidad, entre otros. Por lo tanto, no sólo pensábamos que este vehículo nos iba a dar grandes resultados transcurrido un periodo razonable de tiempo, si no que entendimos que era muy interesante demostrar a la industria que este tipo de activos tienen mucho potencial, si se realiza desde una perspectiva profesional, y que en España deben crearse más vehículos de estas características.

TTR: Udekta Capital se constituyó con un capital inicial de 200.000 euros con la idea de invertir en cuatro o cinco compañías. ¿En qué momento se encuentra el vehículo actualmente? 

J.S.T.: Queríamos empezar con una cantidad pequeña dado que éramos conscientes de los límites de inversión en este tipo de compañías. Hoy estamos por el entorno del millón de euros y hemos pasado de ser 8 accionistas a ser 17 en estos cuatro años y medio de vida del vehículo. Estamos invertidos en 14 compañías. Hemos ido realizando algunas desinversiones y nuestras principales posiciones son: GUILLEMOT, GIGAS, ALTIA e IZERTIS.

TTR: Inicialmente Udekta Capital se centró en compañías que cotizan en el segmento de Empresas en Expansión (EE) no en Socimis y no tenía predilección por ningún sector. ¿Habéis cambiado los criterios?

J.S.T.: Seguimos centrado en las Empresas en Expansión de cualquier sector salvo las SOCIMIS pero hemos dado el salto a las microcaps europeas. Estamos invertidos en dos que cotizan en el Euronext (Paris) y en una que cotiza en el AIM (Londres).

TTR: El Mercado Alternativo Bursátil (MAB) cambió de nombre en 2020 y actualmente se denomina BME Growth, una vez obtenida la categoría de SME Growth Market, otorgada por la Comisión Nacional del Mercado de Valores (CNMV) y reconocida por MiFID. ¿Qué cambios significativos ha habido desde entonces?

J.S.T.: Desde nuestro punto de vista no hay grandes novedades tras el cambio de nombre ni tras la obtención de categoría de SME Growth Market. Sigue siendo un mercado alternativo bursátil dirigido a pequeñas y medianas compañías, aunque es cierto que tiene el sello de calidad de Europa como SME Growth Market y que se abre más al mercado internacional.

TTR: ¿Qué tipo de empresas cotizan actualmente en el BME Growth? ¿Cotizan a precios interesantes? ¿Están obteniendo la rentabilidad que se presupone?

J.S.T.: Siempre encontramos oportunidades interesantes en el BME Growth. Cada vez hay más empresas con proyectos atractivos en expansión. Como en todos los mercados, nos encontraremos buenas y malas compañías. Pero haciendo una buena selección, las rentabilidades son extraordinarias. Los accionistas de Udekta Capital estamos muy satisfechos con los resultados que hemos obtenido en los cuatro años y medio de vida del vehículo. En este periodo, hemos obtenido una rentabilidad de más del doble en nuestras inversiones.

TTR: ¿Qué sería necesario para que el BME Growth en España se sitúe al mismo nivel de mercado en otros países?

J.S.T.: Creo que es necesario que se incorporen más compañías, que exista más información sobre esta clase de activo, que se ofrezca más formación a empresarios para apoyarles en el proceso de incorporación al Mercado y que se explique bien a los inversores todo sobre los riesgos y las oportunidades de invertir en microcaps.

“Hay varios sectores que van a tener una tendencia muy positiva durante los próximos años y que serán interesantes a la hora de invertir. Entre ellos podríamos destacar el sector TIC, la telemedicina y los esports.”

TTR: ¿Cuáles son las claves para que una pyme pueda decidirse a salir a Bolsa en España?

J.S.T.: En términos generales diría que una pyme tiene que tener claro que cotizar en Bolsa es posible y que le aporta muchos beneficios en términos de financiación, visibilidad, notoriedad, liquidez de sus acciones y tener una valoración de la compañía aceptada por el mercado. A partir de ahí, los emprendedores y directivos de las compañías que quieran cotizar en un mercado como el BME Growth tienen que saber que ser una empresa cotizada exige profesionalización, transparencia, presupuestar unos mayores costes de estructura y ofrecer una dedicación especial en materia de relación con inversores.

TTR: El sector tecnológico y el de las energías renovables son los que mayor evolución parecen tener en el sector de M&A y capital riesgo en los últimos meses. ¿Qué sectores apreciáis que tienen mejores perspectivas a medio plazo?

J.S.T.: Desde nuestro punto de vista hay varios sectores que van a tener una tendencia muy positiva durante los próximos años y que serán interesantes a la hora de invertir. Entre ellos podríamos destacar el sector TIC (Tecnologías de la Información y Comunicación), todas las empresas relacionadas con la telemedicina y el sector de los esports.

TTR: En paralelo a la creación de Udekta Capital, nació UDEKTA Corporate como boutique financiera dedicada al asesoramiento a empresas, principalmente en los pasos previos a la salida al MAB. ¿Cómo ha evolucionado vuestra actividad?

J.S.T.: Estamos observando un incremento del interés de las pymes por cotizar y esta situación es muy importante para nosotros. En 2017, creamos Udekta Corporate con el objetivo de asesorar a empresas en distintos ámbitos (legal, financiero, laboral…) y con la diferenciación de ser una boutique especializada en mercados alternativos bursátiles. Sin duda que el crecimiento del número de empresas cotizadas en el BME Growth en estos últimos años y los casos de éxito que está dejando este mercado, como por ejemplo MASMOVIL o GRENERGY, ayudan mucho a atraer más compañías. 

La actividad de UDEKTA Corporate crece año tras año. A día de hoy trabajamos con varias compañías cotizadas en este mercado en el terreno de la Relación con Inversores. Además, estamos asesorando a otras compañías no cotizadas. El plazo que nos solemos poner para coordinar una incorporación a un mercado como el BME Growth se sitúa entre 18 y 24 meses. En este sentido, esperamos que alguna de estas empresas esté cotizando en este mercado en 2022.

“Udekta Sports tendrá vida propia a medio plazo, aunque ahora se está gestando dentro de Udekta Capital y hemos invertido en el Grupo Olympique de Lyon, que tiene diversos activos, además de los equipos de fútbol masculinos y femeninos.”

TTR: A finales de 2019 anunciasteis la creación de UDEKTA Sports, un vehículo de inversión enfocado en los equipos de fútbol europeos que coticen en los mercados de valores. ¿Cómo va este proyecto? 

J.S.T.: Como sabemos, marzo de 2020 fue un mes que nos cambió la vida con la aparición del Covid-19. Teníamos muchas expectativas con el proyecto, pero lo hemos tenido que aparcar durante un tiempo. Lógicamente, crear un vehículo exclusivo para invertir en equipos de fútbol y en cualquier deporte cuando los estadios estaban vacíos, la gente estaba confinada y la incertidumbre era máxima, hizo que pusiéramos el proyecto en “pause”. 

De todas formas, lo que hemos hecho es invertir en un club de fútbol cotizado internacional a través de Udekta Capital. En concreto, hemos invertido en el Grupo Olympique de Lyon que tiene, entre otros activos, a los equipos de fútbol masculinos y femeninos del propio Olympique de Lyon. La tesis de inversión la sustenta casi por sí sola el estadio de fútbol como activo inmobiliario. Para nosotros, este activo valdría bastante más que la capitalización y la deuda del club. El estadio, además de ser el campo donde juega el equipo de fútbol, sustenta otros eventos de empresas, conciertos y muchas actividades aparte de las relacionadas con las del club de fútbol. En realidad, aunque desapareciera el equipo de fútbol, el estadio tendría ya una tasación superior a su valoración en Bolsa. En definitiva, Udekta Sports se está gestando ahora mismo dentro de Udekta Capital pero queremos que tenga vida propia lo más pronto posible.

Dealmaker Q&A

Content available in English and Spanish (scroll down)

TTR DealMaker Q&A with Dentons Cárdenas & Cárdenas Partner Eduardo Cárdenas

Eduardo Cárdenas – Dentons Cárdenas & Cárdenas

Eduardo has more than 40 years of experience and a record of accomplishment that includes several of the most complex, high-value transactions in Colombia’s history. He is the head of the Firm’s Corporate and Mergers and Acquisitions practices and is recognized by major legal directories as a leading Tier I lawyer. His practice benefits from a period as Microsoft Corporation’s senior regional counsel for Latin America as well as from his experience advising local and foreign entities in all major sectors of the Colombian economy including financial services, technology, consumer goods, energy and natural resources, telecoms, and transportation, among others. 


TTR: The technology sector is the most active in the Colombian M&A market year-to-date. What will be the most significant drivers of consolidation in this sector over the medium-to-long term? 

E.C.:  The success of Rappi, Colombia’s first unicorn, has demonstrated that technology generates wealth and opportunities that transcend boundaries. With the pandemic we’ve evidenced that the importance of cash as a method of transaction is diminishing and will be replaced by other more efficient and convenient payment systems. The fintech industry has been very “hot” and will most probably be the target of many M&A deals in the coming months. Consolidation of tech regional players via acquisitions, like the recent purchase of Lagash in Colombia, Uruguay, Chile and Argentina by Mercado Libre, and the entrance of global tech players in the regional market is expected during the next 18 months. 

TTR: How significant a role do you expect foreign tech companies to play in the M&A market in 2021 in Colombia and Latin America? 

E.C.:  Foreign investment is urgently needed in Colombia and the tech sector is not the exception. The role foreign tech companies play in Colombia and in Latin America is part and parcel with the development and growth of the tech sector in Colombia. Fintech has been active the past couple of months through its involvement of foreign tech companies either through technological or capital support. The strong devaluation of the Colombian Peso will increase the appetite of foreign tech companies and private equity funds to perform acquisitions in Colombia.

TTR: Which other sectors in Colombia will attract the most interest from international investors in 2021 and why?

E.C.:  With the wide range of climates and soils, we expect that the agricultural sector will continue to attract international investors, cannabis industry included. Interestingly, we are working on a project (Demetria) that precisely mixes the tech sector with the coffee industry by applying artificial intelligence (AI), which has had a game changing effect in the agricultural sector. This project blends Israeli based technology complemented by local know-how and local and international capital.

TTR: Foreign Private Equity and Venture Capital funds have upped their investments in Colombian companies by 50% YTD in 2021. What elements did the PE and VC transactions that have closed successfully this year have in common?

E.C.:  Both, Private Equity and Venture Capital funds, are constantly looking for opportunities to invest in. By nature, they are looking for greater return on investment and this goes hand in hand with taking more risks. PE and VC are important players in the M&A space and play an important role in making it very dynamic. Most of the acquired companies this year had strong management, healthy balance sheets and were leaders in their geographical market.

TTR: What will be the greatest challenges for Dentons Cárdenas & Cárdenas in its M&A advisory work in Colombia in 2021?

E.C.:  The greatest challenge for us will be responding to an expected added volume of deals that due to Covid-19 have been suspended or postponed. With our geographic coverage in the region, more cross-region work is expected. 


Spanish version


Eduardo Cárdenas – Dentons Cárdenas & Cárdenas

Eduardo cuenta con más de 40 años de experiencia y con una trayectoria que incluye varias de las transacciones más complejas y de alto valor en la historia de Colombia. Enfoca su práctica en las áreas de Derecho Corporativo, Fusiones y Adquisiciones, y Derecho Bancario y Financiero y los principales directorios legales internacionales lo reconocen como un abogado top tier. Su práctica se beneficia de su experiencia como asesor regional senior para Latinoamérica de Microsoft y asesora a clientes locales y extranjeros que pertenecen a los principales sectores de la economía colombiana, incluyendo los de servicios financieros, tecnología, bienes de consumo, retail, energía y recursos naturales, telecomunicaciones y transporte, entre otros.


TTR: El sector tecnológico ha sido el sector más activo en lo que va del año 2021 en el mercado M&A colombiano. ¿Cuáles serán los drivers más relevantes para la consolidación de este sector en el mediano y largo plazo?

E.C.:  El éxito de Rappi ha demostrado que la tecnología genera riqueza y oportunidades que transcienden las dificultades. Durante la pandemia hemos evidenciado que la importancia del efectivo está disminuyendo y que será reemplazado por otros sistemas de pago más eficientes y limpios. La industria de la tecnología financiera ha estado activa y probablemente será el objetivo de muchas fusiones y adquisiciones en los próximos meses. Durante los próximos 18 meses se espera también la consolidación de empresas tecnológicas regionales a través de adquisiciones, como la reciente compra de Lagash en Argentina, Chile, Colombia y Uruguay por parte de Mercado Libre, y a través de la entrada de empresas tecnológicas globales a el mercado regional.

TTR: ¿Qué papel espera que desempeñen las empresas extranjeras de tecnología en las fusiones y adquisiciones en Colombia y América Latina en 2021? 

E.C.: En Colombia, necesitamos inversión extranjera urgente, y el sector tecnológico no es la excepción.

El papel que juegan las empresas tecnológicas extranjeras en Colombia y en Latinoamérica es una parte muy importante del desarrollo y crecimiento del sector tecnológico en Colombia. La industria fintech ha estado activa los últimos meses con la participación de empresas de tecnología extranjeras, ya sea a través de inversión tecnológica o de capital. La fuerte devaluación del peso colombiano aumentará el apetito de las empresas tecnológicas extranjeras y los fondos de capital privado para realizar adquisiciones en Colombia. 

TTR: ¿Qué otros sectores podrían llamar la atención de los inversores internacionales en 2021 y por qué? 

E.C.: Con la amplia gama de climas y suelos, esperamos que el sector agrícola y la industria del cannabis continúe atrayendo inversores internacionales. Actualmente, estamos trabajando en un proyecto (Demetria) que mezcla con precisión el sector tecnológico mediante la aplicación de inteligencia artificial (IA) a la industria del café, impulsando innovación y tecnología en el sector agrícola. Este proyecto utiliza tecnología Israelí complementada con conocimiento y capital local e internacional.

TTR: Fondos extranjeros de Private Equity y de Venture Capital han incrementado sus inversiones en compañías colombianas en un 50% en lo que va del año 2021, ¿Qué elementos tuvieron en común estas transacciones de PE/VC que cerraron con éxito este año? 

E.C.:  Tanto los fondos de Private Equity como los de Venture Capital, están constantemente buscando oportunidades de inversión. Por naturaleza, están buscando un mayor retorno de inversión y esto implica asumir más riesgos. PE y VC son actores importantes en el espacio de fusiones y adquisiciones y juegan un papel importante en hacerlo muy dinámico. La mayoría de las empresas adquiridas este año tuvieron una gestión sólida, balances sanos y eran líderes en su mercado geográfico.

TTR: ¿Cuáles serán los principales desafíos en términos de transacciones de M&A en Colombia durante 2021 para Dentons Cárdenas & Cárdenas?  

E.C.:  El mayor desafío para nosotros será responder y atender al incremento de transacciones de M&A, que debido al Covid-19 se han suspendido o pospuesto. Adicionalmente, con nuestra cobertura geográfica en la región, se espera más trabajo cross-border.